The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.
Used caravan finance can work differently depending on whether you buy from a licensed dealer or a private seller. This guide explains approval conditions, PPSR checks, inspections, seller payments and loan settlement steps for Australian buyers.
Financing a used caravan in Australia can be straightforward, but the process is not always the same as buying new. Lenders usually want to understand the caravan's age, condition, value, registration details and ownership history before they agree to fund the purchase. If you are buying from a private seller, there may also be extra checks around seller identity, payout of existing finance and settlement.
This guide explains how used caravan finance generally works for dealer purchases and private sales, what information lenders may request, why a PPSR caravan check matters, and what usually happens at settlement. It is general information only and does not take your personal objectives, financial situation or needs into account.
Can you finance a used caravan in Australia?
Yes, many Australian lenders may consider finance for a used caravan, including second-hand caravans bought through dealers and private sellers. Approval, interest rates, fees, loan structure and maximum loan amounts depend on the lender's criteria and your individual circumstances.
Common finance options may include:
- Secured caravan loans: the caravan is used as security for the loan. The lender may have conditions about the caravan's age, value, condition and registration status.
- Unsecured personal loans: the loan is not secured against the caravan, but rates and borrowing limits may differ from secured finance.
- Dealer-arranged finance: some dealerships can introduce finance options as part of the purchase process.
- Broker-assisted finance: a broker may help compare lending options and coordinate document checks and settlement requirements.
If you are still comparing finance pathways, you can start with the Caravan Finance Australia overview before narrowing down the type of loan that may suit a used caravan purchase.
Dealer purchase versus private sale caravan finance
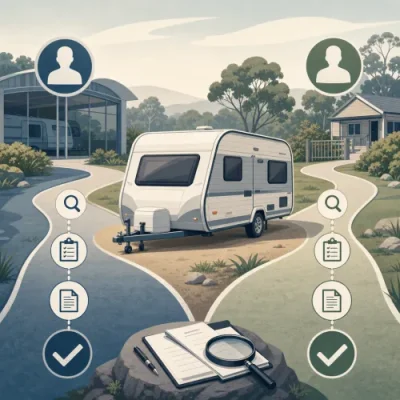
The main difference is the level of documentation and settlement control. Dealers are usually set up to provide invoices, vehicle details and proof of sale in a format lenders recognise. Private sellers can still be financed, but lenders may require more verification before releasing funds.
| Purchase type |
Typical finance considerations |
Common risks to manage |
| Dealer purchase |
Dealer invoice, business details, caravan specifications and settlement instructions are usually easier to verify. |
Understanding dealer fees, optional extras, warranty terms and whether the finance offer is competitive. |
| Private sale |
Lender may request seller identification, bank account details, registration papers, PPSR results, photos, inspection reports or valuation evidence. |
Existing finance owing, unclear ownership, incorrect caravan details, condition issues and settlement timing. |
How used caravan finance usually works
Each lender has its own process, but used caravan finance commonly follows these steps.
- Set a budget: consider the purchase price, deposit, loan repayments, insurance, registration, storage, servicing, accessories and potential repairs.
- Check borrowing capacity: lenders may review your income, expenses, debts, credit history and the amount you want to borrow.
- Find the caravan: identify the make, model, year, VIN or chassis number, registration details, asking price and seller details.
- Apply or update pre-approval: pre-approval can help you shop with a clearer budget, but it is generally conditional until the lender accepts the caravan and the final loan documents.
- Complete caravan checks: this may include PPSR, registration, identity, condition, valuation and insurance checks.
- Sign loan and purchase documents: review the contract, repayment schedule, fees, security terms and any conditions before signing.
- Settle the loan: the lender pays the seller, dealer or existing financier as required, then you finalise transfer and collection arrangements.
Before applying, you may want to estimate repayments using a caravan finance calculator. Calculator results are only estimates and do not guarantee lender approval, rates or final repayments.
What lenders may check on a second-hand caravan loan
A used caravan can be more complex for a lender to assess than a new caravan because condition, value and ownership history can vary widely. Depending on the finance product and provider, lenders may ask for:
- the caravan make, model, year, body type and series;
- VIN, chassis number or other identifying numbers;
- registration details, where applicable;
- purchase price and deposit amount;
- dealer tax invoice or private sale agreement;
- photos or an inspection report, particularly for older caravans;
- evidence of the caravan's market value;
- insurance details before settlement, if required by the lender;
- seller identity and bank details for private sales; and
- a payout letter if the seller still has finance owing.
The caravan's age, condition and resale value may affect whether it can be used as security. Some lenders may be more cautious with older, modified, imported, damaged or unregistered caravans. Others may still consider the application but adjust the loan amount, deposit requirement, loan term or rate according to their criteria.
Why a PPSR caravan check matters
A PPSR check searches the Personal Property Securities Register. For caravan buyers, it can help identify whether there is a registered security interest over the caravan, which may indicate that money is still owed to a financier. It may also show certain written-off or stolen status information where that data is available and applicable.
A PPSR caravan check is especially important for private sale caravan finance because the lender and buyer need confidence that the caravan can be transferred without unresolved finance attached. If there is money owing, the transaction may still be possible, but settlement usually needs to be arranged so the existing financier is paid out correctly.
When checking a used caravan, make sure the identifying number used for the search matches the caravan itself. If the VIN, chassis number or registration details do not match the seller's documents, pause before paying a deposit or signing unconditional paperwork.
How private sale caravan finance works
Private sale caravan finance often has extra moving parts because there is no dealer managing the transaction. A lender may need to verify both the caravan and the seller before it releases funds.
Documents a private seller may need to provide
Private sale requirements differ by lender, but the seller may be asked for:
- a signed sale agreement or tax-style receipt showing the agreed price;
- proof of identity;
- bank account details for settlement;
- registration papers or proof of ownership;
- clear photos of the caravan and identifying plates or numbers;
- a current payout letter if finance is still owing; and
- confirmation that the caravan details match the sale documents.
Some private sellers may be unfamiliar with lender requirements. Explain early that finance settlement may require verification and that the lender may pay them directly rather than transferring loan funds to you first.
Caravan Loan Repayment Calculator
Planning your next caravan adventure? Explore potential repayment scenarios with our Caravan Loan Repayment Calculator. Adjust loan amounts, interest rates and repayment terms, and view amortisation charts to better understand potential repayments and interest costs over time.
If the seller still owes money
If a PPSR check shows an existing security interest, do not assume the seller can simply pay it off later. In a financed private sale, the settlement process may involve paying the existing lender first, then paying any balance to the seller. The exact process depends on the current financier, the new lender and the sale price.
For example, if the agreed sale price is more than the existing loan payout figure, settlement might clear the seller's loan and the remaining amount may go to the seller. If the payout figure is higher than the sale price, the seller may need to cover the shortfall before the security interest can be removed. Do not rely on informal promises; wait for written settlement instructions and confirmation from the relevant parties.
Paying deposits in a private sale
A deposit may help secure the caravan, but it can also create risk if finance is not approved or if checks reveal a problem. If you pay a deposit before formal approval, consider using a written agreement that clearly states whether the deposit is refundable and what happens if finance, inspection or PPSR checks are not satisfactory. You may wish to obtain independent legal or consumer advice before signing a binding contract.
How dealer used caravan finance works
Buying a used caravan from a dealer may be simpler from a paperwork perspective. Dealers can usually provide a formal invoice, Australian Business Number details, settlement instructions and information about optional extras, delivery and warranty terms.
However, convenience does not automatically mean the finance is the right option for you. It is still worth comparing:
- the interest rate and comparison rate;
- application, establishment, monthly and early payout fees;
- loan term and total interest payable over the life of the loan;
- whether the caravan is secured against the loan;
- optional extras such as extended warranties, insurance products or accessories; and
- what happens if settlement or delivery is delayed.
A dealer may offer to arrange finance, but you are not limited to that option. You can compare dealer finance against bank, non-bank lender and broker-arranged options before deciding.
Inspection and valuation considerations before finance settlement
Finance approval does not replace your responsibility to check the caravan carefully. Lenders focus on credit risk and security value; they do not necessarily confirm whether the caravan is suitable for your travel plans or free from defects.
For a second-hand caravan, consider checking:
- water damage, leaks, soft floors and roof condition;
- chassis condition, rust, suspension, brakes and tyres;
- gas, electrical and plumbing systems;
- appliances, batteries, solar panels and accessories;
- ATM, GTM, tare weight and compatibility with your tow vehicle;
- service history, repair records and modification history; and
- whether the layout and payload suit your intended use.
For broader buying checks, the guide on buying a second-hand caravan can help you think through inspection and negotiation points before you commit.
Caravan loan settlement: what actually happens?
Caravan loan settlement is the point where the finance provider releases funds according to the approved loan conditions. The money may go to a dealer, a private seller, an existing financier or a combination of parties.
Settlement may involve:
- final approval of your loan application;
- signed loan documents and direct debit authority;
- confirmation of comprehensive insurance, if required;
- verification of the seller's payment details;
- payout of any existing finance;
- payment of the balance to the seller or dealer; and
- confirmation that security interests and ownership transfer steps are being handled correctly.
Do not collect the caravan or allow the seller to release it before you understand the settlement timing and ownership transfer requirements. If funds are sent late in the day or close to a weekend, bank processing times may affect when the seller sees the payment.
Common issues that can delay used caravan finance
Used caravan finance can be delayed when information is missing, inconsistent or difficult to verify. Common causes include:
- the VIN or chassis number does not match the registration or PPSR search;
- the seller has not provided identity or bank details requested by the lender;
- there is existing finance owing and no current payout letter;
- the caravan is older or modified and needs extra valuation or inspection checks;
- insurance has not been arranged before settlement;
- the purchase contract is incomplete or unclear;
- the buyer's income or expense documents need updating; or
- the lender requires a higher deposit or different loan structure than expected.
If you are working to a tight pickup date, build in time for checks and avoid assuming that finance approval and settlement will happen on the same day.
Questions to ask before financing a used caravan
Before you sign a contract or loan agreement, consider asking:
- Is the loan approval conditional on inspection, valuation, insurance or PPSR results?
- Will the lender pay the seller directly?
- What happens if the seller has finance owing?
- Is my deposit refundable if finance is not approved?
- Are there fees for early repayment, missed payments or loan changes?
- Does the loan term make sense for the caravan's age and expected useful life?
- What is the total cost of the loan, not just the repayment amount?
- Are optional extras being financed, and do I understand their cost?
- What insurance is required before settlement?
- When can I safely collect the caravan?
If you want help coordinating lender requirements, seller documents and settlement steps, the broker support page explains how broker assistance may fit into the caravan finance process. Availability and outcomes depend on your circumstances and provider criteria.
Final thoughts
Used caravan finance is not just about getting a loan approved. The lender, buyer and seller all need confidence that the caravan is correctly identified, fairly represented, able to be financed and ready for settlement. Dealer purchases are often more structured, while private sale caravan finance may require extra checks around PPSR, seller identity, existing finance and payment instructions.
Taking time to confirm the caravan details, understand the loan conditions, compare finance options and manage settlement carefully can reduce avoidable surprises. Before committing, make sure the caravan suits your budget, towing setup and travel plans, and seek professional advice if you are unsure about the financial or legal implications of the purchase.
Published: Tuesday, 11th Aug 2026
Author: Paige Estritori



Private sale caravan finance sounds doable, but I’d be doing the PPSR before handing over any deposit after nearly getting caught once.